
Blog > Higher Mortgage Rates and Gulf Coast Inventory: What's Changing This Fall
Higher Mortgage Rates and Gulf Coast Inventory: What's Changing This Fall
by
By Randy Richardson, Broker Associate, The 4th Right Team
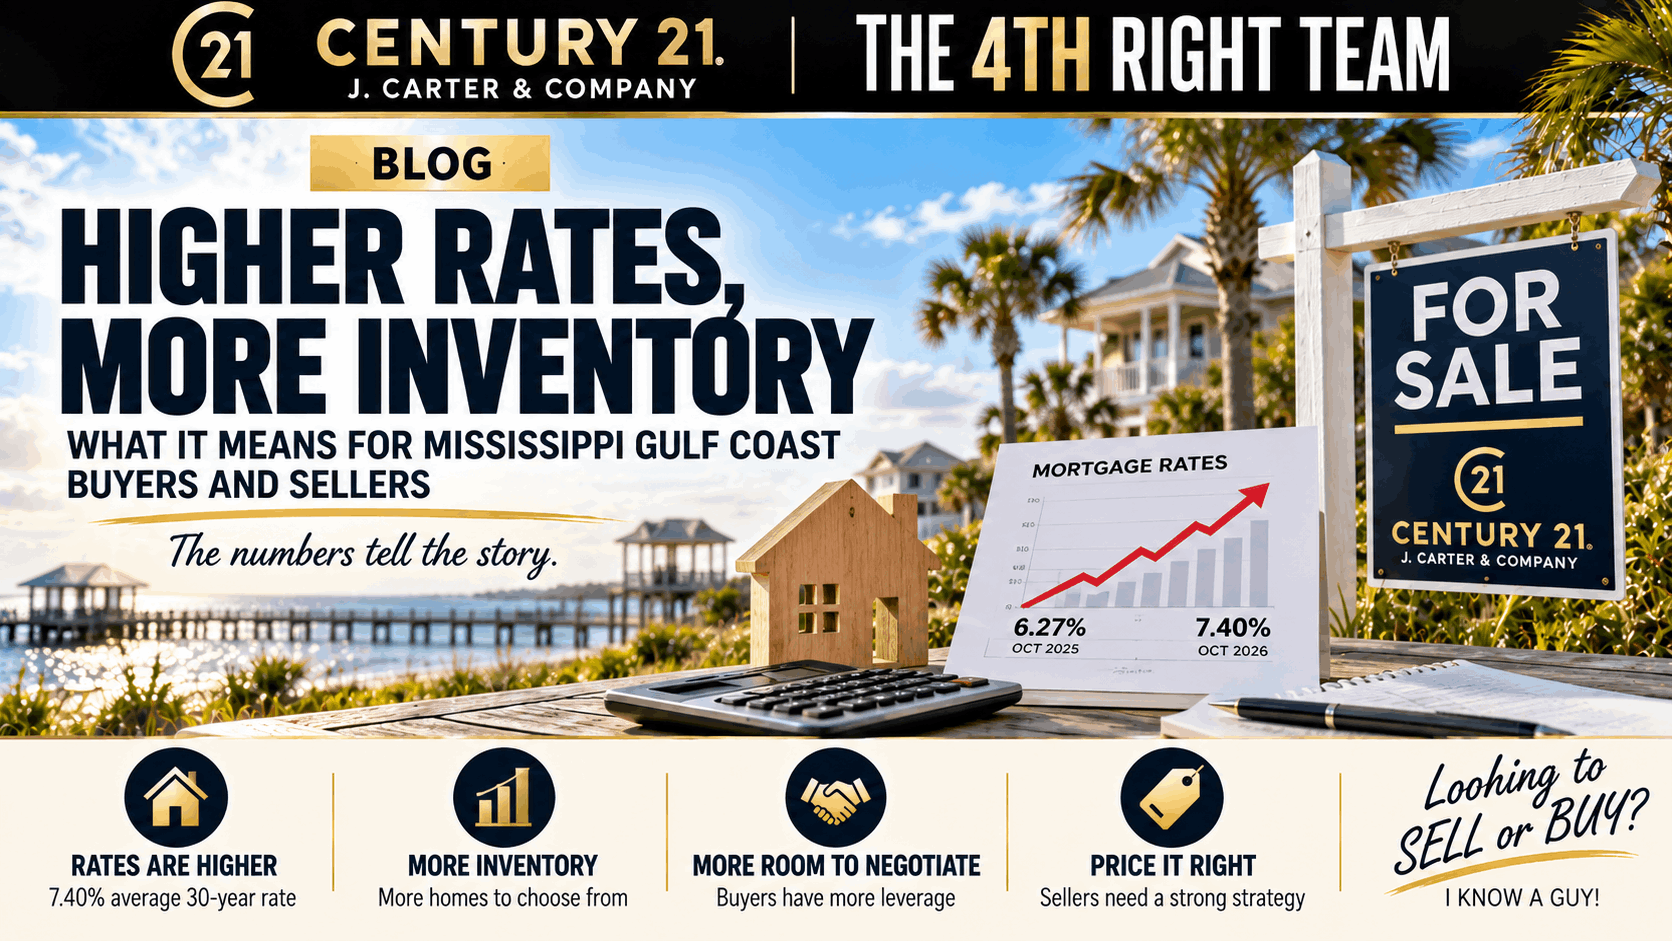
Quick Answer: Higher mortgage rates are slowing Mississippi Gulf Coast sales and letting inventory build. As of October 15, 2026, Freddie Mac put the average 30-year fixed rate at 7.40%, up from 6.27% a year earlier. On the Coast, the Gulf Coast Association of REALTORS reported 2,488 homes for sale in August 2026, up 5% from a year before, while sales fell 10% and days on market rose to 71. For buyers, that means more choice and more room to negotiate. For sellers, it means pricing right from day one matters more than it has in years.
Why are mortgage rates going up again in 2026?
Rates climbed for seven straight weeks into early October, and Freddie Mac's average hit 7.40% the week of October 8, 2026. That's the highest since November 2023. It held at 7.40% the following week.
Mortgage rates follow the long-term bond market more than the Fed. When investors demand more to hold 10-year Treasuries, mortgage rates follow. Back in August, I wrote about waiting for rates when Freddie Mac's average was 6.65% as of August 20. Two months later, it's three quarters of a point higher.
I don't know where rates go next, and nobody else does either. What I can tell you is what higher rates are doing to the Coast market right now.
Why does inventory grow when mortgage rates go up?
Higher rates push on inventory from two directions at once. They shrink the number of buyers who qualify, so homes take longer to sell. They also keep some owners with low rates from listing at all.
The first force is winning on the Coast. Listings are piling up faster than buyers are taking them. GCAR's August 2026 numbers show 519 sales, down 10% from 581 a year earlier, while inventory rose 5% to 2,488 homes. Homes sat an average of 71 days, up from 58.
Nationally, the picture matches. Realtor.com's September 2026 report showed active listings up 5.4% from a year earlier. In the South, median list prices were down 2.4%. Just over one in five listings nationwide had a price cut, the highest September share since 2018.
Is the lock-in effect still keeping Coast homeowners from selling?
Less than it used to. FHFA's National Mortgage Database showed 50.6% of outstanding U.S. mortgages had a rate under 4% at the end of 2025. That's still half of all borrowers holding a rate they'll never see again.
But the share at 6% or higher had climbed to 21.9%, the highest since 2015. Every year more owners are people who bought or refinanced at today's rates. They don't feel trapped by their mortgage, so job changes, PCS orders, growing families and downsizing still put homes on the market.
That matters here more than most places. The Coast has steady turnover from Keesler, NCBC Gulfport and Ingalls. Those moves happen on a schedule, not on a rate chart.
How much do higher rates change a monthly payment?
On a $250,000 loan, principal and interest at 6.27% runs about $1,543 a month. At 7.40%, it's about $1,731. That's $188 more a month, or about $2,260 a year, before taxes and insurance.
Flip it around and it's even clearer. A payment that covered a $250,000 loan a year ago now covers only about $223,000. That's roughly $27,000 less house for the same budget, and it's a big reason sales slowed. You can run your own numbers on my mortgage calculator.
On the Coast, insurance can move the payment as much as the rate does. Get both numbers before you shop.
What do higher rates and more inventory mean for Coast buyers?
You have more homes to pick from and more room to negotiate than you did a year ago. With homes sitting longer, sellers are more open to credits, repairs and price talks.
Ask about seller-paid rate buydowns. A seller credit that buys your rate down can do more for your payment than a small price cut. A lender can show you both side by side.
Look for assumable loans too. Some Coast sellers have VA or FHA loans at rates far below today's. Taking one over isn't simple, but I walk through when assumable VA loans are worth it and when they aren't.
What do higher rates and more inventory mean for Coast sellers?
Your price has to be right on day one. Buyers can see days on market, and overpriced listings sit. A stale listing usually ends up selling for less than one priced right from the start.
Expect buyers to ask for help with closing costs or a buydown. Know your bottom line before the first offer, and run your numbers on a seller net sheet. If you have an assumable VA loan, say so in the listing. It can be a real edge, and I explain how in selling with an assumable VA loan.
None of this is a crash. Prices on the Coast were still up 3% year over year in August. I covered why in worried about a housing crash. What's changing is who has the upper hand in a negotiation, and it's tilting toward buyers.
By the Numbers
Freddie Mac 30-year fixed average, October 15, 2026: 7.40%
Same average a year earlier: 6.27%
Coast homes for sale, August 2026 (GCAR): 2,488, up 5% year over year
Coast homes sold, August 2026 (GCAR): 519, down 10%
Coast average days on market, August 2026 (GCAR): 71, up from 58
Coast average sales price, August 2026 (GCAR): $257,275, up 3%
U.S. active listings, September 2026 (Realtor.com): up 5.4% year over year
U.S. mortgages with a rate under 4%, end of 2025 (FHFA): 50.6%
The Bottom Line
Higher rates haven't broken the Coast market. They've slowed it down and handed buyers more choices. If you're selling, price for the market you're in, not the one from two years ago, and start with a home value evaluation. If you're buying, get pre-approved, get an insurance quote, and use the extra time and inventory to your advantage. My buyer's guide walks you through it.
Frequently Asked Questions
What is the average mortgage rate right now?
As of October 15, 2026, Freddie Mac's average 30-year fixed rate was 7.40%, unchanged from the week before and up from 6.27% a year earlier. Freddie Mac updates it every Thursday.
Is inventory going up on the Mississippi Gulf Coast?
Yes. The Gulf Coast Association of REALTORS reported 2,488 homes for sale in August 2026, up 5% from a year earlier, while sales fell 10%.
Is it a buyer's market on the Gulf Coast?
It's moving that way. At August's pace, Coast inventory would take about 4.8 months to sell, and homes averaged 71 days on market. Buyers have more room to negotiate than they did a year ago.
Should I wait for rates to drop before buying?
Nobody can time rates. If you buy now, you get more choice and negotiating room, and you can refinance later if rates fall. Base the decision on your budget and timeline, not a forecast.
Will higher rates make Coast home prices fall?
Not so far. GCAR's average sales price was up 3% year over year in August 2026. What higher rates have changed is how long homes take to sell and how much sellers negotiate.
Sources
Freddie Mac, Mortgage Rates Hold Steady at 7.40%, October 15, 2026. Current and year-ago 30-year and 15-year averages: https://freddiemac.gcs-web.com/news-releases/news-release-details/mortgage-rates-hold-steady-740
Freddie Mac Primary Mortgage Market Survey. Weekly rate history: https://www.freddiemac.com/pmms
Fox Business, Mortgage rates rise to 7.4%, October 8, 2026. Seventh straight weekly increase, highest since November 2023: https://www.foxbusiness.com/economy/mortgage-rates-10-8-2026
Realtor.com September 2026 Housing Report, September 30, 2026. National and South active listings, list prices and price cuts: https://finviz.com/news/396855/price-cuts-reach-yearly-high-as-inventory-nears-pre-pandemic-levels-realtorcom-september-housing-report
FHFA National Mortgage Database, Q4 2025, as reported by Calculated Risk, April 1, 2026. Share of outstanding mortgages under 4% and at 6% or higher: https://calculatedrisk.substack.com/p/fhfas-q4-national-mortgage-database
Gulf Coast Association of REALTORS, Gulf Coast Market Stats, August 2026. MLS United data for Hancock, Harrison, Jackson, George, Greene, Stone and Pearl River counties: sales, average sales price, days on market and inventory: https://gcarealtors.com/member-services-2/gcar-gulf-coast-market-stats
Payment figures: principal and interest on a $250,000, 30-year fixed loan, calculated by The 4th Right Team at 6.27% and 7.40%.
About the Author
Randy Richardson is a Broker Associate and Team Leader of The 4th Right Team at CENTURY 21 J. Carter & Company. He serves buyers and sellers across the Mississippi Gulf Coast.
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
📞 Office: (228) 731-3881 | Cell: (228) 547-9999
📧 realtorrandyrichardson@gmail.com
🌐 www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!