
Blog > How to Price a Gulf Coast Home When the Comps Mix Storm Rebuilds and Originals
How to Price a Gulf Coast Home When the Comps Mix Storm Rebuilds and Originals
by
By Randy Richardson, Broker Associate, The 4th Right Team
Quick Answer: On the Mississippi Gulf Coast, a pre-Katrina original and an elevated post-2005 rebuild can sit on the same street with the same square footage and still be two different products. Averaging their price per square foot gives you a number that fits neither house. Price off comps of the same type first, then adjust for elevation, insurance cost, roof and systems age. Fannie Mae requires appraisers to base adjustments on how the market actually reacts, so the seller who documents those differences, with an elevation certificate, permits and an insurance quote, gives the appraiser what it takes to support the price.
Why do storm rebuilds and originals throw off Coast comps?
Because the numbers that go into a quick price check don't show what buyers are really paying for.
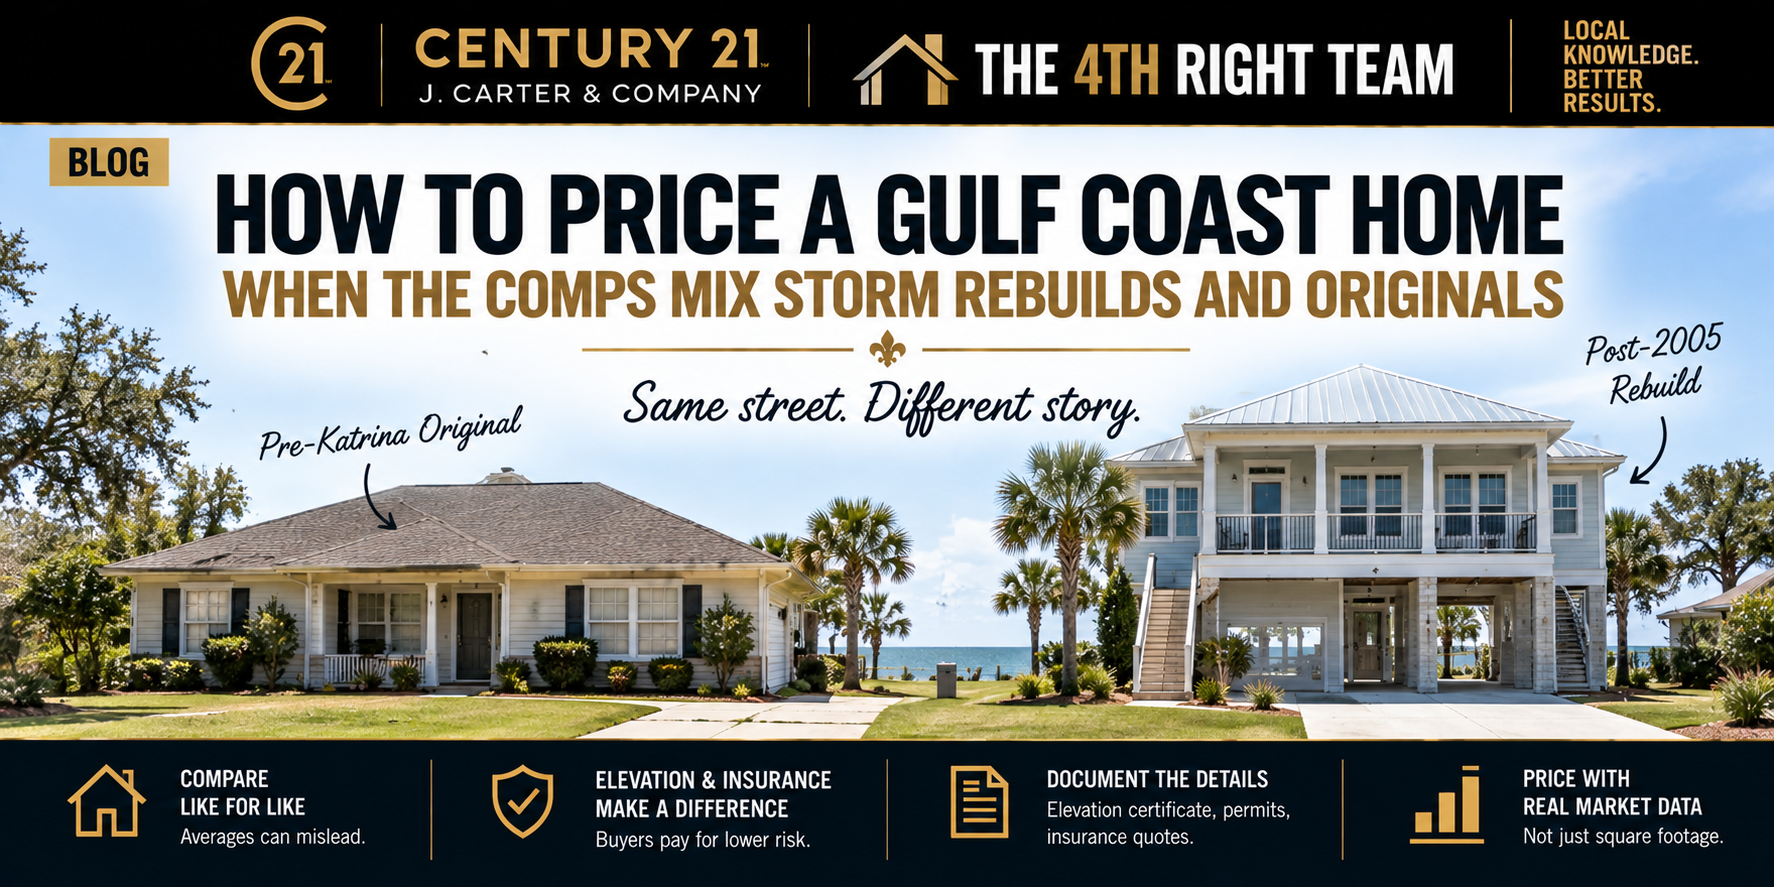
After Katrina, whole blocks south of the tracks came back one lot at a time. Some owners rebuilt higher to newer codes. Some repaired the house that was there. Twenty years later, a street in Long Beach or Pass Christian can have a 1965 slab ranch next to a 2009 home on pilings. On the MLS they may both show three bedrooms and 1,600 square feet.
Blend those sales into one price per square foot and you get an average that overprices the original and underprices the rebuild. The original sits. The rebuild leaves money on the table. That's how overpriced listings sit even when the seller used "real" comps.
What makes a post-Katrina rebuild worth more than an original?
Mostly the monthly cost of owning it. Buyers don't just compare prices. They compare payments, and on the Coast insurance is a big part of the payment.
Elevation is the biggest piece. Kelsey Carlson, CISR Elite, a Personal Lines Risk Advisor at Lemon Mohler Insurance, told me the elevation data drives the flood premium. In an AE zone, a slab home at or below base flood elevation and a home on stilts 20 feet above it are completely different rate stories. That's why the elevation certificate matters so much in these comparisons.
Code is the next piece. Homes built after the post-Katrina code changes were built for higher wind loads, which I cover in my pre-Katrina versus rebuild post. A FORTIFIED roof or a completed wind mitigation form can lower the wind coverage cost too.
But don't assume the rebuild always wins. The first rebuilds are 16 to 20 years old now. Their roofs, water heaters and air conditioners may be due, and roof age can hurt insurability no matter when the house was built. Some buyers also don't want stairs, or the small footprint an elevated lot allows. And an original that was fully renovated and sits above base flood elevation may compete head to head.
How much is lower insurance worth in the price of a home?
More than most sellers expect. Here's a simple way to see it.
Say a rebuild's flood and wind premiums run $150 a month less than the original next door. At the 6.95% average 30-year rate Freddie Mac reported as of September 17, 2026, $150 a month covers the principal and interest on about $22,660 of loan. In plain terms, a buyer can pay roughly $22,000 more for the rebuild and have about the same monthly payment. At $100 a month the gap is about $15,100. At $200, it's about $30,200.
That's an illustration, not a rule. The real number depends on the actual quotes for each house, which is exactly why you get one. Insurance is where the difference shows up, so start with how much insurance costs on your address before you pick a list price.
How does an appraiser adjust between a rebuild and an original?
By what the market actually paid for the difference, not a formula. Fannie Mae's guidelines say an appraiser's adjustments must reflect the market's reaction to the difference between properties. They also say two homes can share the same condition or quality rating and still need an adjustment.
Fannie Mae also requires appraisers to rate condition and quality on each property's own merits, not by comparing it to the neighbors. So a rebuild doesn't get an automatic bump just for being newer than the street.
The best evidence is paired sales, meaning a rebuild and an original that sold close together on similar lots. On a thin street there may not be any, and that's when the appraisal can come in short. Hand the appraiser your elevation certificate, permits, roof date, and any FORTIFIED or wind mitigation paperwork. They can only use what they can see.
How should I price my home if the comps are mixed?
Sort first, then price. Here's how I do it for sellers.
I split the recent sales into rebuilds and originals, then compare yours to its own group. If your group has too few sales, I widen the area before I cross over. In thinner markets like Pass Christian, monthly medians swing on a handful of sales, so I price off homes with similar square footage and lot size, not the headline median. When I do have to use the other group, I adjust for elevation, roof and systems age, and a real insurance quote on your house, and I write down why.
For an original, that often means a lower price than the street average, but a price buyers will actually pay. That beats a string of price cuts later. For a rebuild, it means pricing above the blended average and backing it up with paperwork in the listing, so the buyer and the appraiser both see the value.
If your home is on the water, the same logic applies to the kind of waterfront it is. A canal lot and a beachfront lot don't comp against each other either.
By the Numbers
Age of the earliest post-Katrina rebuilds in 2026: about 16 to 20 years
Average 30-year fixed rate, Freddie Mac, as of September 17, 2026: 6.95%
Loan amount covered by $100 a month at that rate: about $15,100
Loan amount covered by $150 a month: about $22,660
Loan amount covered by $200 a month: about $30,200
Fannie Mae limit on net or gross appraisal adjustments: none, as long as they're market-based
The Bottom Line
On the Coast, the street isn't the comp. The type of house is. Price a rebuild against rebuilds and an original against originals, and use elevation, insurance and age to bridge the gap when you have to cross over. Then document it, because the appraiser can only support what you can prove.
If you're not sure which group your house belongs in, start with a home value evaluation. I'll pull the comps by type and show you how I price and list a Coast home so it holds up at appraisal.
Frequently Asked Questions
Is a post-Katrina rebuild worth more than an original home on the Gulf Coast?
Often, but not always. Rebuilds built higher and to newer codes usually cost less to insure, which buyers pay for. An older rebuild with an aging roof, or a renovated original above base flood elevation, can close that gap.
Should I use price per square foot to price my Coast home?
Only within the same type of house. Averaging rebuilds and originals together overprices one and underprices the other.
How do appraisers handle storm rebuilds as comps?
Fannie Mae requires market-based adjustments, ideally supported by paired sales. Give the appraiser your elevation certificate, permits and roof date so they can support the difference.
How much does lower insurance add to a home's value?
It depends on the quotes. As an illustration, at a 6.95% rate as of September 17, 2026, every $100 a month in savings covers about $15,100 of loan.
Sources
Market-based adjustments and no limit on net or gross adjustments: Fannie Mae Selling Guide B4-1.3-09, Adjustments to Comparable Sales
Condition and quality rated on the property's own merits, same rating can still need adjustment: Fannie Mae Selling Guide B4-1.3-06, Property Condition and Quality of Construction
30-year fixed rate as of September 17, 2026: Freddie Mac Primary Mortgage Market Survey
Elevation data and flood premiums: Kelsey Carlson, CISR Elite, Personal Lines Risk Advisor, Lemon Mohler Insurance, written answers, September 2026
Loan amounts per monthly savings: calculated for this post at 6.95% on a 30-year fixed loan, illustrative only
[ADD SOURCE: Mississippi Insurance Department page on wind mitigation and FORTIFIED premium discounts]
About the Author
Randy Richardson is a Broker Associate and Team Leader of The 4th Right Team at CENTURY 21 J. Carter & Company. He serves buyers and sellers across the Mississippi Gulf Coast.
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
📞 Office: (228) 731-3881 | Cell: (228) 547-9999
📧 realtorrandyrichardson@gmail.com
🌐 www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!